Published 2026-09-27 · 26 min read
The Cairo-founded mobility company that began as a bus-sharing app, agreed to list on Nasdaq at an implied $1.5 billion valuation, nearly shut down months after listing, and rebuilt itself as a transport operator for employers across Egypt and the Gulf. Now it is heading for the United States.
"Swvl was built to fill buses with commuters who could not afford Uber. It came back as a company that fills buses for employers who can. Whether that model travels is the question the next two years answer."
Start with what very few companies ever do. In November 2022 Swvl announced it would cut more than half its remaining staff and leave almost every market it had entered. Weeks later it opened a strategic review whose disclosure mentioned bankruptcy protection. Its founder now says the rational decision was to shut it down. He didn't. Four years later the company is growing again – revenue up 68% in its latest quarter – still listed, newly funded, and winning multi-year contracts with Saudi banks and hospitals and new clients in the UAE and Kuwait. This piece is about what was rebuilt, and whether it can become bigger than what was lost.
2-Minute Brief
Three arguments run through this piece. Each is a conclusion, not a fact – I show the evidence, and you can disagree.
Argument 01
The comeback is real, and it happened in a specific order.
First survival: creditors accepted 85% haircuts, acquisitions were sold or unwound, headcount fell from 606 to 203. Then rebuilding around employers instead of commuters. Then growth: revenue up 41% in 2025 and 68% in the first quarter of 2026.
Argument 02
The business that came back is not the one people remember.
84% of 2025 revenue came from companies paying to move their staff. The consumer app most Egyptians know has drifted: its Egyptian reviews now run overwhelmingly negative, and the service they describe is not the one that earns the money. Swvl has put employers ahead of the consumer brand in its home market.
Argument 03
The Gulf proves the model works. The US tests whether it travels.
Gulf revenue grew 111% in Q1 2026, priced in Gulf currencies tied to the dollar. The US is the prize the founder keeps returning to – and the market where the leading rivals have raised or hold many times Swvl's capital.
Before the Analysis
If you have never used it, here is the mechanism – because everything that follows depends on it.
Greater Cairo is home to more than 20 million people, and for most of them the commute means a crowded public bus or an informal microbus with no schedule. In early 2017 Mostafa Kandil left Careem and started Swvl with Ahmed Sabbah and Mahmoud Nouh, on EGP 400,000 of savings – about $25,000 – and three rented buses. His framing of the customer was blunt: "the 99% who can't pay for Uber every day."
The trick was that Swvl owned nothing. It paid bus owners a fixed daily rate – Kandil says about EGP 590 a day for four trips – planned the routes with its own software, and sold the seats. That is the whole model: software that fills seats on vehicles someone else owns.
The shift from the first row to the second and third is the story of the company. A commuter rides when they feel like it; an employer signs for three to five years. The first built a famous brand. The second built revenue you can plan around.
⚑ Primary Observation
Swvl's own releases say it returned to profitability in 2025. Both halves of that sentence deserve a closer look – the growth is better than most people assume, and the profit is weaker than the headline suggests.
✓ What has genuinely been rebuilt
△ Where the 2025 profit came from
Where the 2025 profit came from
Swvl's 2025 annual report. "Running the business" is revenue less the cost of buses and drivers and less overheads, before financing and tax.
A word on why I am writing about this company at all. Few founders anywhere take a business from three rented buses to a Nasdaq listing in five years, and fewer stay when it nearly disappears – Kandil describes his net worth going to zero, moving back in with his mother, lawyers threatening him daily, and almost nobody left in the office. The problem Swvl set out to solve, how people who cannot afford a car get to work, has not gone away in Cairo or anywhere else it operated.
My scepticism is narrower. The rebuild gets told in interviews as a feat of endurance and almost never as a business, and the part that would persuade me – how the creditors were settled, what was sold, what the operating model is now – lives only in the filings. On the numbers this is a $24M company with 324 people, and the ambition belongs against that base, not against the twenty-country map of 2022.
Survive, Rebuild, Grow
The rise is well known. What happened after is not. In his long-form interviews the founder tells it as a personal story; read in sequence, the filings tell the operating one.
2017–2021 · The rise
From three buses to a Nasdaq listing
An $8M Series A in 2018, then a $42M round in 2019, at the time the largest ever for an Egyptian startup. In July 2021 Swvl agreed to merge with Queen's Gambit, a listed shell company, at an implied $1.5B valuation, on a pitch projecting more than $1B of gross revenue by 2025. It then bought companies in Spain, Argentina, Turkey, Germany and Mexico, mostly paying in shares – what its then-CFO called "a way to grow without cash."
March 2022
The listing that raised $164.8M of the $445M it had lined up
The deal closed on 31 March 2022, five weeks after Russia invaded Ukraine and as rates began rising. Holders redeemed roughly 85% of the $345M sitting in trust, so Swvl raised $164.8M gross against the $445M it had lined up. By then it called itself "100+ cities across 20+ countries."
May – December 2022 · Survive
Cut
Staff cut 32% in May 2022, then more than half again in November, and a December strategic review whose disclosure mentioned bankruptcy protection. Payroll fell from 606 at the end of 2021 to 203 a year later; Kandil puts the peak at about 1,700, counting the acquired teams.
2023
Sell and settle
A 1-for-25 reverse split to stay listed. Thirteen settlements, mostly with creditors from the SPAC deal, cut $18.7M of what was owed by 85%. Pakistan was wound down and the company handed over – 99.99% of it for $20,000. Urbvan, bought in 2022 for $27.6M in shares, went fourteen months later for $12M in cash. Every other acquisition was unwound or liquidated.
2024–2025 · Rebuild
Kandil: "the exact opposite of what we did"
Kandil's diagnosis was specific: revenue in local currencies against costs in dollars, through devaluations in Egypt, Pakistan, Argentina, Turkey and Kenya. The rebuild answered it directly – a regional headquarters in Riyadh, metro shuttles for Saudi Awwal Bank staff, a software-only contract with almajal G4S, a UAE relaunch and a first UK contract – with every new market chosen for hard-currency revenue.
2026 · Grow
Back to growth, back to the market
Nasdaq compliance regained in April. Kuwait launched in January. Q1 revenue up 68%. In August and September, about $14.5M of new money led by Coefficient, a Houston firm Swvl describes as backed by the Sawiris family – earmarked for the US, a lending product for transport operators, and the balance sheet. On 22 September, a new city and a new kind of customer: 24/7 shuttles for seven hotels in Madinah, carrying pilgrims and hotel guests.
Revenue by year, $M
2025 revenue is still below 2021 and less than half of 2022 – though the peak years included acquired businesses that no longer exist. The shape is a V with a long bottom.
Swvl annual reports, revenue as originally reported. Swvl counts the full fare as revenue.
Where the revenue comes from
Swvl only began splitting revenue by region recently, so this is the whole public series: the 2025 full year against the latest quarter. In nine months the Gulf went from a third of revenue to nearly half. What the filings never split by country is employers versus consumers – so nobody outside can say how much of Egypt's revenue is still riders buying seats.
2025 annual results and Q1 2026 results. Gulf covers Saudi Arabia, the UAE and Kuwait. Shares are rounded.
By the Numbers
From Swvl's 2025 annual report (filed April 2026) and its Q1 2026 results (June 2026), unless stated otherwise. Half-year 2026 results were not yet out when this was written.
Up 41%. Egypt $16.2M (67%), Gulf $8.0M (up 122%).
$8.2M in the quarter. Gulf up 111%, Egypt up 45%.
2025. The consumer app brought in about $3.9M, down 8%.
Q1 2026, down from 128% in 2025. The Gulf was 105%.
How the $24M is built
Many mid-sized contracts, not a few giant ones – the largest announced are "up to" $1.5M to $6.3M over three to five years. Swvl had 34 active accounts in Saudi Arabia at the end of 2025, and no industry is more than 20% of revenue. It discloses neither its customer count nor its largest client. The company runs on 324 people, 266 of them in Egypt, with operating costs down to 23% of revenue.
The margin is thin
Gross margin was 18.2% across 2025, down from 20.9% in 2024, and 19.4% in the first quarter of 2026. That blended figure sits between the two halves of the business – about 17% on employer contracts, about 22% on consumer rides. Swvl books the full fare as revenue and pays most of it to vehicle owners, keeping $4.4M of gross profit on $24.2M.
What the market says it is worth
The August–September round sold about 10 million shares and warrants at around $1.45, roughly doubling the share count. The stock ran from $1.47 before the announcement to an intraday high of $8.48, then settled back to $4.09 on 25 September – roughly $75–85 million, depending on whether 2 million near-free warrants are counted, against the implied $1.5 billion at the SPAC. It moves daily; treat it as a range.
Ownership changed too. Coefficient held 38.9% of ordinary shares when its investment closed on 1 September (about 37% after a smaller investor closed later), plus a board seat and consent rights over decisions such as delisting or taking the company private. On his last disclosed holding of 2.3 million shares, Kandil owns roughly 12% of the enlarged company, down from about 23%.
Who Swvl moves (logos on swvl.com)
An unnamed retail client, on swvl.com
Swvl's intelligent transit platform transformed how our employees commute across our 14 retail branches. By booking rides directly through the app, they no longer rely on our fleet manager for coordination.
e& Egypt
At e&, our hybrid model requires smart, adaptable transport solutions. Swvl's tech-enabled system handles fluctuating office schedules with ease, reducing both our commuting costs and operational headaches.
Bank AlJazira, in numbers
More than 100,000 bookings on Swvl shuttles for Bank AlJazira staff in Saudi Arabia since the start of 2025.
Testimonials as published on swvl.com; only e& is attributed to a named company. The Bank AlJazira figure is from a Swvl announcement, November 2025.
Product Quality Audit · Public Surface
The same app serves an employee whose company pays and a traveller booking a seat to Alexandria. The first group renews. The second writes the reviews.
Radar · Swvl, scored /10
The shape is lopsided on purpose. Everything that serves a paying employer scores well. Everything a consumer touches alone scores badly.
Scorecard
App Ratings · Stars vs What People Write
One caution: Swvl publishes a single rider app and a driver app, with no separate business app, so an employee on a company shuttle and a traveller heading to Alexandria review the same place – and most never say which they were. What the record shows is that the mood differs sharply by country.
App Store ratings by storefront. Review themes are drawn from the written reviews across both storefronts.
Critical · iOS Egypt, September 2026
The vehicles are often in terrible condition, drivers don't seem to be properly trained, and scheduled ride times are inaccurate. Their customer care chat is useless, don't expect anyone to get back to you.
What It Could Build
This part is mine, not Swvl's. Each idea is anchored in something a comparable company already does, and each carries the objection I would expect from whoever has to build it. One number frames them all: Swvl capitalises $684,000 of software and spends about $518,000 a year on technology, down from $1.1M two years ago. Engineering salaries sit inside staff costs, so this is not the whole picture – but it is not a company that can buy its way to a new product either.
01
A commute is an hour of someone's day, and Swvl treats it as transport. Vonlane in Texas puts 22 seats where a coach fits 50 to 56, adds an attendant, charges $99 to $159, and is still adding routes twelve years on. Swvl sells to employers, so tiering is natural: a standard shuttle, and a quieter one with proper seats and working Wi-Fi inside a richer contract. The objection: the vehicles belong to the operators, so the better cabin is someone else's spending decision – unless Swvl starts specifying or owning them, which is a far more capital-hungry company.
02
Companies already pay for staff to travel between offices, to sites and to airports, and that time is dead. A vehicle fitted for work – a table, a screen, a connection – booked like a meeting room turns the journey into something the employer buys rather than tolerates. Landline sells coach seats inside airline tickets; Napaway, which sold lie-flat sleeper seats on overnight coaches, moved to charter when scheduled service stopped paying. The objection: a vehicle used twice a week earns nothing on the other days.
03
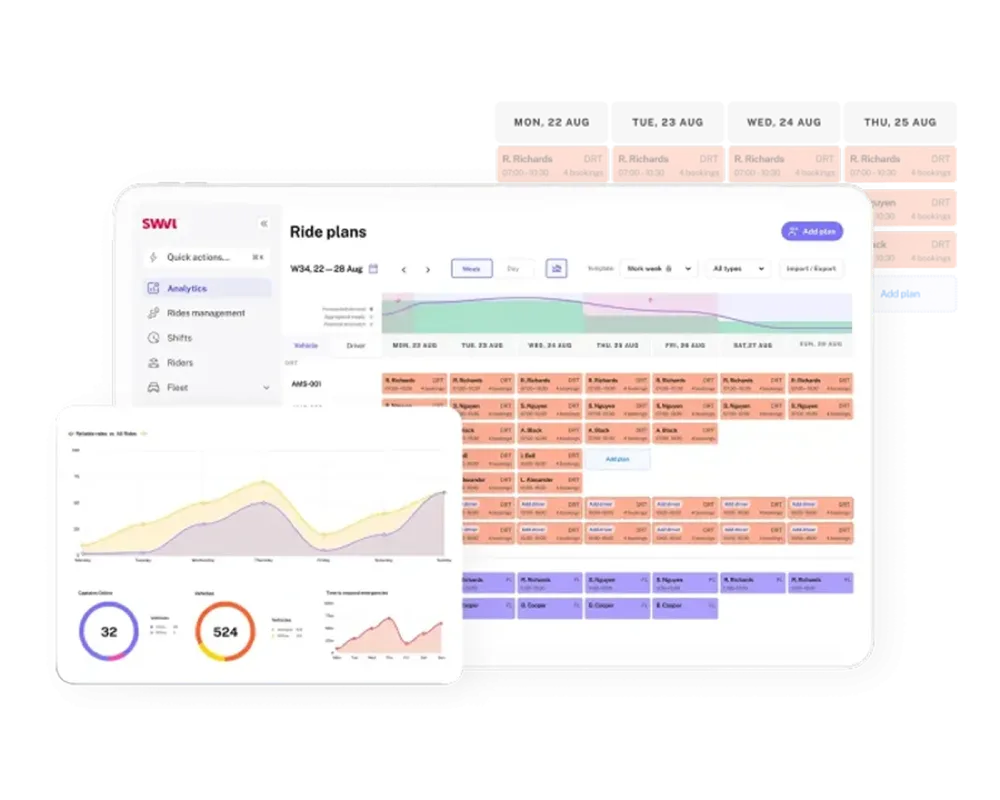
Zeelo's client portal advertises service levels, cost per rider, operator spend and missed bookings. Zum tells districts that transport-related absences fell 86% at Kansas City Public Schools. Swvl's dashboard, pictured below, is built around operations – utilisation, reliability, skipped stations, ratings – with no cost-per-rider or service-level view. It collects the data; it just doesn't sell the answer back. The objection: publishing reliability cuts both ways, and unanswered support is Swvl's most common complaint.
04
Zeelo ships "Sustainability Insights"; Volt Lines reports a 37% cut in emissions per passenger. Swvl's pages name no emissions metric anywhere, while it sells to the Gulf employers who now publish sustainability reports – and it has already run an electric bus in Saudi Arabia. Every filled seat is a car off the road, and nobody counts it for the customer. The objection: it is a number Swvl would report, not a change in how it operates – useful to a client's ESG team, no help to the margin.
What the client actually sees
Swvl's own product page for the admin dashboard, September 2026. Ride plans, captains online, vehicles in service – the view an operations team needs, and no cost per rider, service level or spend.
The 11-Star Test · The Daily Commute
Start at five stars – the ride that simply went as expected – then ask what six looks like, then seven, and keep climbing to an eleven that is deliberately absurd. Walking back down from absurd shows moves you can't see at five.
Deliberately absurd, and that is the point. Nobody commutes. Swvl knows who is coming in before they do, and the vehicle that arrives suits the day – a quiet cabin to finish work in, a meeting room on wheels when the team travels together, a car when a bus makes no sense. The employer stops buying transport and starts buying its people's time back.
The commute becomes a benefit, not a bus. Staff choose how they travel within an allowance the employer sets, the hour on board is usable, and HR can see what it bought: attendance, retention, cost per head, carbon saved.
The trip adjusts to you. Routes follow hybrid schedules, delays reach you before you leave home, and a missed pickup has a fallback rather than a phone number nobody answers.
The company shuttle that shows up. A fixed seat, live tracking, and a reported 97.6% first-station on-time rate. Clients renew and expand. Better than the offline contractors it replaces.
A seat, when the bus comes. Delays, same-day cancellations, charges for trips that didn't happen – and no one to call. That is the pattern across the written reviews.
Next 24 Months
First the direction of travel, because the rest of this section is about what it hasn't solved: operating costs fell from 34% of revenue to 23% in a year, and the quarterly operating loss narrowed about 70% to $174,000. Five risks follow, each measurable, ordered by how likely they are to bite first.
01 · Already biting
The annual report splits revenue and cost by type: $20.27M of employer revenue against $16.75M of cost, $3.90M of consumer revenue against $3.06M. That is 17% on the part that is growing, 22% on the part that is shrinking, so every point of growth pulls the blend down. Watch for: employer margin below 17% in the next annual report. Consequence: breakeven then needs about $9.8M of quarterly revenue, a fifth above the last quarter, or a margin above 23% – which Swvl has never reached as a public company. What the filings never say is whether those three-to-five-year contracts re-price for fuel and wages mid-term, which is the single term that decides whether the margin holds.
02 · Already biting
Money owed by clients grew 48% and unbilled work 75%, against revenue up 41%. Swvl bills monthly on 30 to 60-day terms, yet the balance is worth about 94 days of revenue, up from 83 – invoices settle roughly a month late, and a quarter of the book is already written down as doubtful. Watch for: collection beyond 105 days, or a bad-debt charge above $1M. Consequence: the bank facilities are small next to a $6.1M book growing 53% a year, so the money raised from investors ends up financing clients' slow payment rather than growth.
03 · Dated
The August–September investors bought at about $1.45 and took 9.97 million shares and warrants – 53% of the enlarged count. Their 180-day lock-ups end in early March 2027. Watch for: the share price near $1.86, where the market value of Swvl's listed shares falls under Nasdaq's $35M threshold. Consequence: a crowded exit into a thin stock, and a listing question returning after only a year of peace.
04 · Internal
Of the $38.2M backlog, $19.8M is management's estimate of renewals, which the filing itself calls not contractually committed, and contracts are announced as "up to" values with no minimums. Meanwhile Gulf clients expanded 5% last quarter against 35% the year before. Watch for: Gulf retention below 100%, which would mean existing clients shrinking. Consequence: the recurring-revenue story weakens exactly where growth is supposed to come from.
05 · Internal
Press boilerplate lists seven countries; the annual report lists five. The UK is one unnamed customer, Kuwait a launch and a $2.2M contract with the client unnamed, and Qatar has appeared in releases since April with no launch or contract. The US has no named customer, and the last two wins were announced without a value after five that carried one. Watch for: a named US contract with a number. Consequence: announcements stop moving the story, which matters for a company that has to raise again.
Competitive Intelligence
Swvl's competition depends on the map. In Egypt the ride-hailing giants have left shared rides. In the Gulf the incumbent is the traditional contractor – which, as the moat section shows, is sometimes also the customer. In the US it meets companies with more capital and a decade more history: Via since 2012, HopSkipDrive since 2015, Zeelo about ten years old, against Swvl's 2017 start.
Via sells transit software and operations to cities and agencies in more than 30 countries. One quarter of its revenue is more than five years of Swvl's.
The closest mirror of Swvl's model – software plus third-party operators, sold to employers – and further ahead on the client-facing side, advertising service-level and cost-per-rider reporting Swvl's pages don't mention. Swvl agreed to buy Zeelo in 2022, cancelled, and forgave a $10M loan to it.
Swvl's US school service targets students the yellow bus doesn't reach – exactly the niche HopSkipDrive built its business on, while Zum chases whole district contracts with electrification and outcome data.
Uber discontinued its Egypt shuttle in April 2026 and Careem Bus closed in 2020, leaving the traditional transport contractor as the thing Swvl says it replaces. Tripix launched in April 2026 with the same employer-first model.
Positioning Map
The set splits into two camps: companies that run vehicles in a few places very well, and software platforms that sell into many. Swvl sits in between – it can run the buses or license the software. That flexibility wins mid-sized Gulf deals, and against a specialist in either camp it means being second-best at both.
My own placement, from each company's product pages and disclosures. Directional, not measured.
The North Star
Worth asking plainly, because the answer changes what good looks like. Kandil talks about being the first Middle Eastern company to go to America and not be a secondary player there. That is a destination, not a model. Three models are available, and they pay very differently.
The software platform is Via: sell planning and dispatch, keep software margins, let someone else own the buses. The contract operator is Transdev or Keolis: run networks under long contracts at operator margins, defended by incumbency. The regional platform is the Careem path Kandil came from: own the demand, then sell more to it.
Swvl today is the middle one wearing the first one's clothes: it books the full fare and pays most of it to bus owners, which is an operator's economics, while its language and its 18% margin sit awkwardly against a software story. The genuinely new thing it has found is narrower and more interesting than any of the three: nobody has built the technology layer for the Gulf's institutional transport – banks, hospitals, schools, and now hotels moving pilgrims in Madinah. Those journeys happen today, run by contractors on phones and spreadsheets, and Swvl reaches them both directly and by selling to the contractors themselves. That is not a category the world is waiting for. It is a position worth holding. Whether Swvl is winning it is not something the public record can settle, because no one discloses share of this market – including Swvl.
The Moat, Stress-Tested
Swvl's defence, stated plainly, is that clients renew and expand. That is true, and it is worth less than it sounds. Here is what the accounts show when you look for the lock.
✓ What is real
Nine years of running buses in Cairo traffic is not nothing. Swvl has the operator relationships, route history and incident record a new entrant needs years to build, and clients renew: 114% retention last quarter, 128% across 2025. Contracts run three to five years, and replacing one means replanning routes and moving every rider to a new app mid-term. In the Gulf it has what wins tenders – named banks and hospitals already served, and a Riyadh base that makes it eligible for work outsiders cannot bid for.
△ What the filings show is thin
One customer complicates the story. Swvl's flagship software contract is with almajal G4S – itself a large Saudi contractor, the kind of company the competitive section says Swvl displaces. Selling software to contractors may be the better business, but it makes Swvl a supplier to the incumbent rather than its replacement, and a contractor that has run your dispatch system for three years is well placed to do without you at renewal. Clients also pay nothing up front: customer advances were zero in 2025, so Swvl funds a 94-day receivable for them. Contracts are "up to" ceilings with no disclosed minimums, priced per route rather than per rider. And the technology is smaller than the story implies: $684,000 of capitalised software, a technology line down 54% in two years to $518,000, and no research line or patents disclosed. Volt Lines – the Turkish company Swvl bought and then unwound – offers employers the same rider app, client portal and routing tools, and raised $3M of asset-backed debt to do it.
Businesses shaped like this become hard to replace in four known ways. Contract incumbency, the Transdev model, where switching a city's transport is a political act – Swvl is building this, without the depots that make incumbents immovable. Supply density – Swvl has it in Egypt, but its operators are third parties who can work for anyone. Living inside payroll and HR systems, as employee-benefit platforms do, so removing you means unpicking payroll – nothing on Swvl's product pages suggests it connects to either. Financing the vehicles – lending operators the money to buy the buses they then run for you, so leaving means refinancing. Moove does this for drivers in emerging markets; Swvl announced a version of it in September.
Product Org & Culture
Swvl today is a very different organisation from the roughly 1,700-person company Kandil describes at its peak. The annual report lists two executive officers: Kandil, who is also chairman, and CFO Ahmed Misbah. Co-founder Ahmed Sabbah left as CTO in 2021 to start Telda and remains on the board, alongside former CFO Youssef Salem, BECO Capital's Dany Farha, and now Coefficient's Abdalla Ali.
Talent signal
Across 335 reviews, spanning the growth years and the 2022 cuts. A steady score for a company that went through what Swvl did, though it can't be split by year from the outside.
Structure signal
The rebuilt company runs on country VPs – the UAE, Saudi Arabia and Kuwait, and one for the US – with engineering, finance and operations moved to Egypt and Pakistan to cut costs. The UAE lead describes the team as "intentionally staying lean." It is efficient, and it puts a lot of weight on very few people as new markets open.
Founder signal
Kandil calls the 2022 cuts "the hardest thing in my life" and speaks openly about needing time to recover afterwards – candour that is rare in a listed-company CEO. The rebuild ran on a small team; the next phase asks for a much faster pace.
Forward View
Demand is not the variable – employers keep signing. Three other things are: the margin, the cash the growth consumes, and March 2027, when the lock-ups end and half the share register can be sold.
Bear
The employer mix keeps pulling margin toward 17%, receivables keep absorbing cash, and the US and Madinah both need funding before either earns. The new money goes on the gap, and when the lock-ups end a stock that ran hard meets sellers who paid $1.45. Signal: another raise inside twelve months, or a widening operating loss at the half year.
Base
Saudi Arabia keeps compounding – banks, hospitals, now hotels in Madinah – and the Gulf passes Egypt during 2027. Swvl crosses breakeven on Gulf volume rather than a margin breakthrough, and the US stays a small experiment. A good outcome, and a smaller one than the founder describes. Signal: a full year of operating profit without one-off income.
Bull
A US district or employer signs and says so publicly, a loan book to operators appears in the accounts, and the pilgrimage work becomes a repeatable business rather than one client with seven hotels. Then Swvl is the rare emerging-market company exporting an operating model rather than importing one. Signal: US revenue disclosed as its own line.
Closing Thought
Swvl is not the biggest mobility company anywhere, and this piece has not pretended otherwise. In one category it is the reference: technology-run transport for the Gulf's institutions – banks, hospitals, schools, and, since last week, hotels moving pilgrims through Madinah – a contract whose value it has not disclosed. It is listed on Nasdaq, holds the first licence Egypt's regulator issued under its 2018 ride-app law, and has rebuilt all of that from a company that almost died, which almost nobody manages. What it is not yet is durable. The business that is growing earns the thinner margin, growth is consuming cash rather than producing it, and what holds clients is largely the disruption of changing supplier rather than anything Swvl owns outright. Kandil wants to be the first Middle Eastern founder to take a company to America and not be a secondary player there. The nearer question is whether being indispensable to the institutions of one region is the bigger prize – and whether Swvl can make that pay before its investors want an answer.